Artificial intelligence has changed rental application fraud in a practical way: a document can look professional, internally consistent, and completely plausible without being authentic. The problem is no longer limited to spotting a clumsy fake pay stub or an obviously altered driver's license. AI tools can lower the effort required to create convincing income records, manipulate identity documents, and build applicant files that survive a quick visual review.
For Richmond rental owners, that changes the job of screening. PMI James River's tenant screening and risk-control process is built around verifying material facts rather than deciding whether paperwork simply looks credible. The broader Rental Fraud in Richmond guide covers the larger fraud landscape. This article addresses the narrower operational question: what has AI changed, and what should landlords verify differently because of it?
Key Takeaways
- AI has made convincing false documents and manipulated identities easier to produce, which reduces the value of appearance-based screening.
- A document that looks real is evidence to verify, not proof by itself.
- Modern fraud controls increasingly combine identity, document, source, behavioral, and cross-file signals rather than relying on one check.
- Fraud-detection tools should help establish what is authentic. Written screening criteria should still control the qualification decision.
- Richmond landlords should not apply national fraud percentages to the local market, but the operational problem applies anywhere digital applications and remote verification are used.
AI Has Changed What Rental Application Fraud Looks Like
The most important change is not that fraud suddenly exists. It is that the cost of producing convincing false evidence has fallen.
In an August 2026 survey of 1,400 landlords and property managers, Checkr reported that 67% of respondents said AI-generated fraud had become harder to catch than a year earlier. The same survey found that 55% had caught or suspected a situation in which the person who moved into a unit was not the person who applied.
Those figures are national survey results, not Richmond fraud rates. There is no reliable evidence in these sources showing that 67% or 55% applies to Richmond City, Henrico, Chesterfield, Hanover, or the Richmond Metro generally. Their value is different: they show how quickly the screening environment is changing.
AppFolio's 2026 Property Manager Benchmark Survey found a similar tension. Among 1,617 U.S. residential property-management professionals, 56% reported encountering application fraud during the previous year, and 65% of that group reported multiple types of fraud. At the same time, 78% expressed confidence in manual document verification.
That combination is worth paying attention to. Operators can feel comfortable reviewing documents manually while the documents themselves become easier to manipulate.
TransUnion describes the same shift as a growing trust gap. Its 2026 analysis identifies synthetic identities, manipulated or AI-generated income documents, and coordinated fraud across properties as emerging threats. Its central distinction is useful: screening now has to establish that the underlying information is valid before evaluating what that information says about the applicant.
Why Visual Document Review Is No Longer Enough
Traditional fraud review often begins with visible irregularities: strange fonts, inconsistent spacing, bad math, an employer logo that looks wrong, or a photograph that appears edited. Those checks still have value. They are becoming less reliable as the primary control.
The existing PMI James River guide to fake pay stubs in rental applications makes the narrower income-verification point: a polished PDF should not carry the decision. AI makes that principle more important because a fraudster can potentially create several polished pieces of evidence rather than one.
A pay stub can agree with an employment letter. An altered ID can contain the expected name and date of birth. A fabricated application can be internally consistent. When the same person controls all of the information being submitted, agreement between applicant-provided documents is weaker evidence than agreement with an independent source.
That is why the operational question has shifted from Does this look authentic? to What independently establishes that this information is authentic?
The change is already visible in screening technology. RentEngine's 2026 Fraud Guard 2.0 release, for example, says its ID review looks for image-manipulation indicators such as pasted portraits, inconsistent image characteristics, screen-capture patterns, and security-feature irregularities. It also combines document checks with live-selfie, phone, location, and behavioral signals.
Those features are useful as an illustration of where fraud prevention is heading. They are not a universal formula, and a vendor flag by itself should not become an improvised qualification criterion.
What Richmond Landlords Need to Verify Differently
PMI James River's experience across the Richmond Metro is that screening failures do not occur at one predictable point. Income verification can fail. Rental history can fail. Identity and fraud controls can fail. A correct verification can even be lost during a handoff or overridden when vacancy pressure makes an incomplete file feel complete enough.
AI does not change that underlying process problem. It changes the quality of the evidence entering the process.
1. Verify identity as a separate question
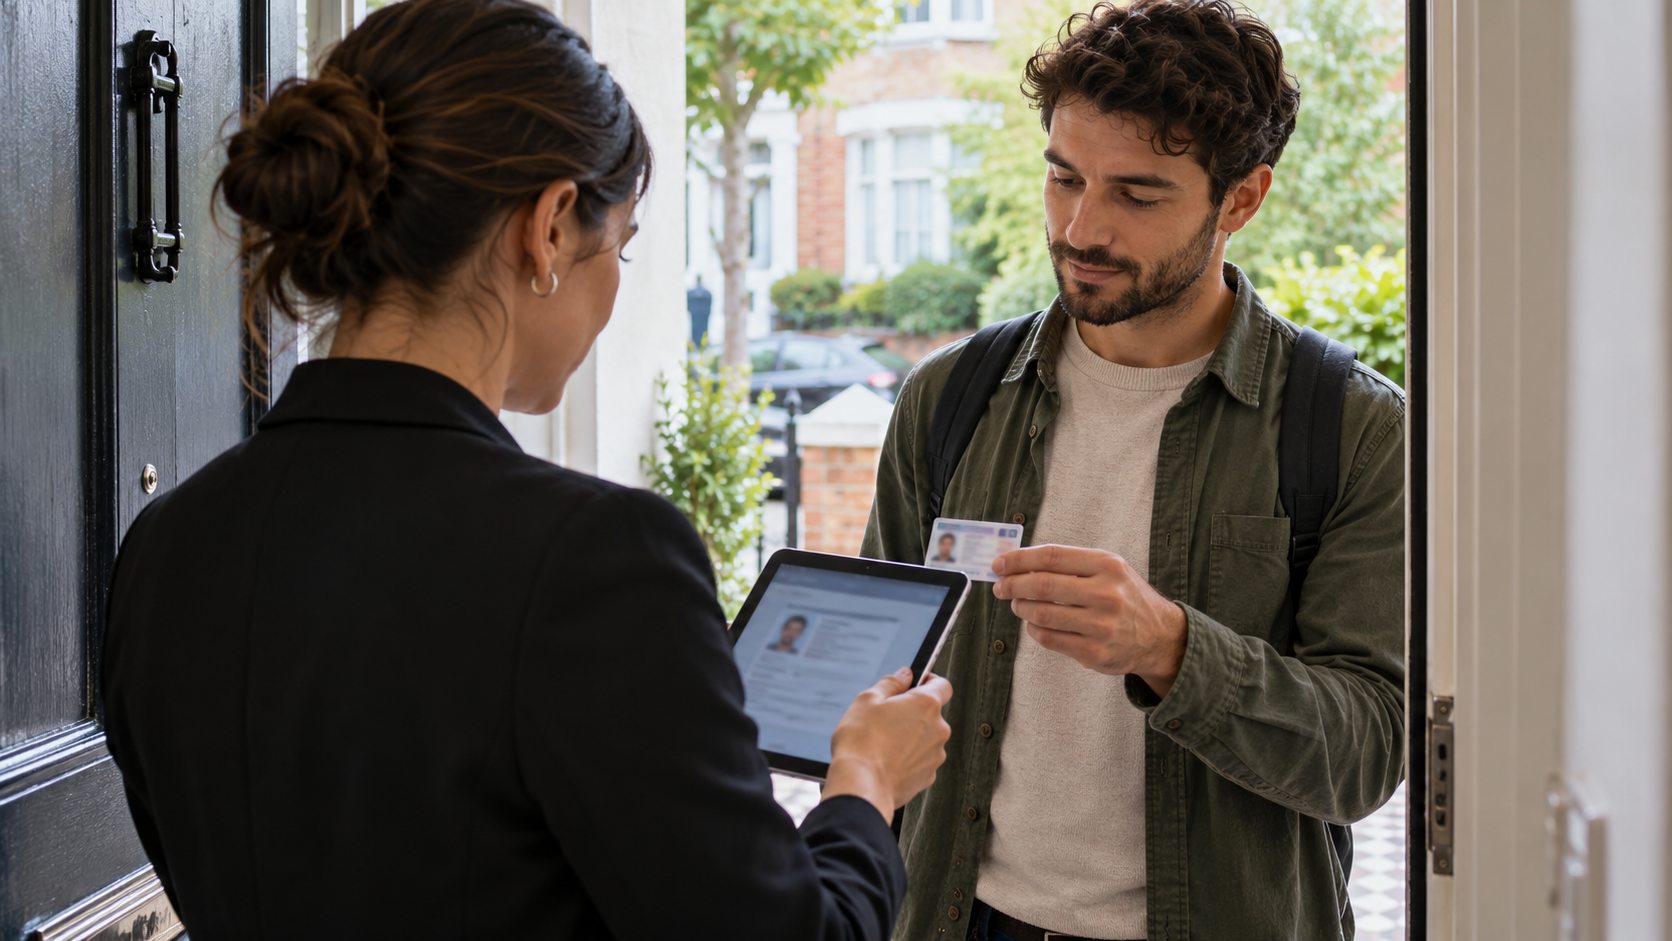
An applicant providing an ID is not the same as establishing that the applicant is the person represented by that ID. Modern identity controls may include live capture, liveness checks, biometric matching, document authentication, phone verification, or other corroboration.
The objective is not to turn a landlord into a forensic examiner. It is to avoid making one uploaded image the entire identity test.
2. Treat income documents as claims that need corroboration
AI-generated or manipulated payroll documents make one-document income policies increasingly fragile. Where appropriate, the stronger approach is to establish whether independent evidence supports the same income claim.
That may mean comparing payroll documentation with verified deposits, confirming employment through an appropriate independent channel, or using a direct-source income-verification system. The proof path can vary with the applicant's legitimate income type. The qualification standard should not drift merely because the evidence format changes.
3. Separate document consistency from source independence
Three documents that agree with one another are less persuasive when all three came from the same applicant and could have been created from the same false information.
A modern file should make clear which evidence is applicant-provided and which information came from an independent or controlled source. That distinction becomes more important as fabricated documents become easier to make consistent with one another.
4. Use behavioral signals as a reason to verify, not as a substitute for criteria
Fraud prevention is also moving beyond documents. RentEngine, for example, describes behavioral checks involving repeated showing requests, unusual geographic patterns, repeated prescreening failures, and interest across properties with very different rents.
Behavior can identify a file that deserves additional verification. It should not become a shortcut for deciding that a person is unqualified. A flag answers the question, What needs to be checked? The screening criteria answer the different question, Does the verified applicant qualify?
5. Make incomplete verification visible
This may be the least glamorous control and one of the most important. A screening workflow should make it obvious when identity, income, rental history, consumer reports, or another required step remains unresolved.
That principle is central to PMI James River's broader guide to why tenant screening is a process problem, not a people problem. AI-generated fraud makes a controlled workflow more valuable because the risk can move from one part of the file to another. Adding one sophisticated fraud tool does not repair a process that can still approve an incomplete application.
Keep AI in the Evidence Layer, Not the Final Decision
There is an obvious irony in responding to AI-enabled fraud with more AI. In many cases, that is exactly what modern verification systems are doing. Machine-assisted tools can examine document characteristics, compare identity signals, recognize patterns across transactions, and surface inconsistencies that would be difficult for one person to recognize manually.
The useful boundary is between detecting evidence and making the housing decision.
A fraud-detection system can indicate that an ID may have been manipulated. An income-verification system can show that reported payroll information does not reconcile with the source data. A screening platform can identify a consumer-report result. Those outputs still need to enter a defined decision process with established qualification criteria, clear decision authority, and a record of what evidence supported the outcome.
This matters for compliance as well as operations. The Federal Trade Commission's landlord guidance on consumer reports explains that when information in a consumer report contributes to an unfavorable rental decision, Fair Credit Reporting Act adverse-action requirements can apply. A new fraud-detection tool does not make the rest of the screening workflow disappear.
The strongest operating model is therefore not “let AI decide.” It is also not “ignore AI and keep reviewing PDFs by eye.” It is a layered system in which technology helps establish whether the evidence can be trusted, while consistent screening criteria control the leasing decision.
Conclusion
AI has not created a completely new category of rental fraud. It has made existing forms of fraud cheaper to produce, easier to scale, and harder to identify through appearance alone.
For Richmond landlords, the practical response is not to become better at guessing whether a document is fake. It is to reduce how much the decision depends on unverified applicant-provided information in the first place.
Identity should be verified as identity. Income should be corroborated as income. Material conflicts should be resolved before approval. Behavioral or technology-generated fraud flags should trigger the appropriate verification step rather than creating a new subjective screening standard. The final file should show how verified evidence connected to the same qualification criteria used for other applicants.
Owners who do not want to build and maintain that screening control chain themselves can review PMI James River's Richmond tenant screening and risk-control process. AI may keep changing the fraud tools on both sides of the transaction. A disciplined verification process is what keeps the decision standard from changing with them.
Published: October 15, 2026