Yes. For an investor whose rental properties are concentrated in one region, adding Richmond, Virginia, can be a sensible way to spread geographic exposure. The purchase still has to work on its own numbers, and the owner needs a dependable way to operate it locally. Owning properties in two cities is not automatically better than owning well-selected properties in one.
Our Richmond real estate investment services approach acquisitions through achievable rent, property condition, operating expenses, and management feasibility. Our guide to finding good rental investment deals in Richmond covers property-level due diligence. Here, the question is broader: when does adding Richmond as another market improve an investor's overall portfolio?
Key Takeaways
- A second metro can reduce dependence on one local economy, but interest rates, financing conditions, and other risks can affect both markets.
- Richmond's size and growth make it worth evaluating, not automatically worth buying. Current rental competition and property-specific economics matter more than a favorable market slogan.
- Compare complete acquisition costs, financing, reserves, vacancy, capital improvements, and ongoing management before deciding where to expand.
- A local property-management operation makes it practical to own a Richmond rental without living nearby.
- Investors already based in Richmond may find worthwhile ways to expand locally before taking on the complexity of another metro.
What Does Diversifying Into Another Rental Market Actually Accomplish?
Geographic diversification is primarily about reducing dependence on a single local market. If every rental is exposed to the same major employers, building cycle, insurance environment, and local rental conditions, the properties may perform similarly when those conditions change.
Buying in Richmond can add a different regional source of rental income for an investor whose existing properties are elsewhere. That can be valuable even when the new acquisition is the same basic asset type, such as another single-family home. But it introduces another set of local contractors, leasing conditions, property taxes, insurance considerations, and operating rules.
Adding a second property within the Richmond region can diversify individual-property risk, tenant turnover, repair schedules, and possibly property type. It does not provide the same geographic separation as owning in two metropolitan areas. The right decision depends on the concentration risk the investor is trying to address and the cost of addressing it.
Does Richmond Make Sense as a Second Rental Market in 2026?
Richmond is a substantial metro rather than a single rental neighborhood. The U.S. Census Bureau's July 2025 estimate put the Richmond metropolitan population at approximately 1.39 million, compared with approximately 1.37 million a year earlier, as reported in the Federal Reserve Bank of St. Louis population series. That establishes the scale of the market, but it does not establish the rent or investment return of any particular property.
The near-term picture is more complicated. In September 2026, the Richmond metro's preliminary unemployment rate was 3.8%, while payroll employment was down 1.0% from a year earlier, according to the Bureau of Labor Statistics. Our fall 2026 Richmond rental-market update also documents greater advertised rental competition in parts of the region. A growing metropolitan population and a softer current leasing market can both be true.
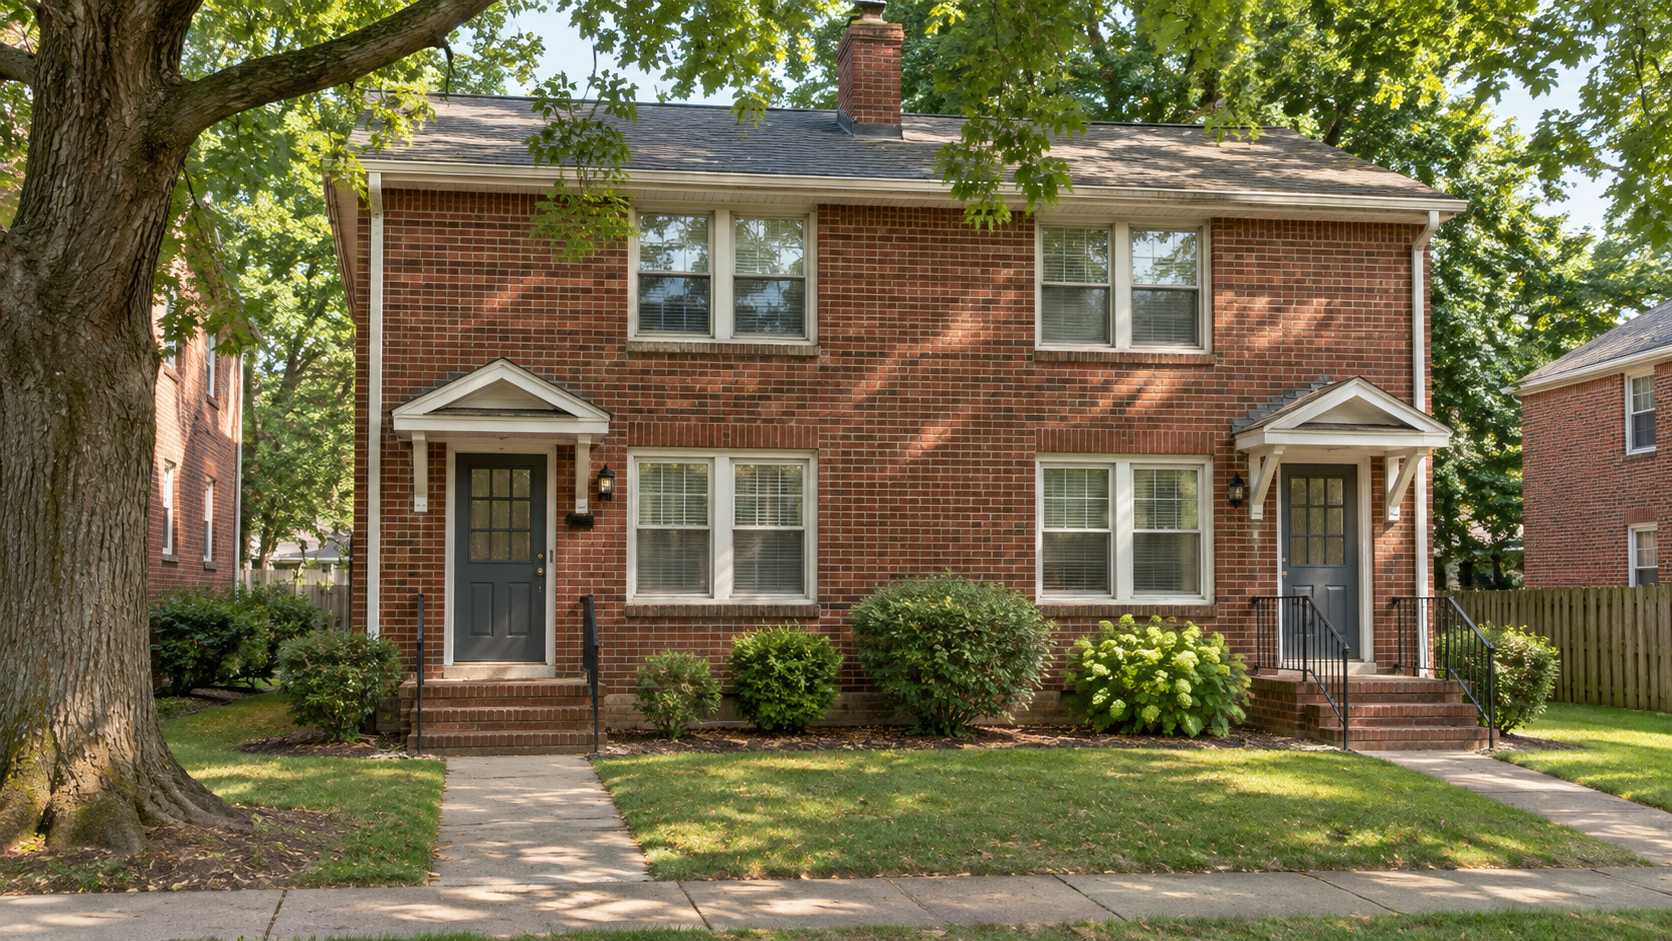
That is a reason to underwrite carefully, not to dismiss the market. A Richmond City duplex, a Henrico townhome, a Chesterfield single-family house, and a Hanover rental may face different competing listings, property expenses, and maintenance needs. The relevant rental market is the one a prospective resident actually shops, not an average covering the entire metro.
Property type matters too. A single-family home offers one rent stream, while a duplex or fourplex offers multiple units with different shared-system and turnover considerations. Our single-family versus multifamily investment comparison explains those distinctions for Richmond buyers.
Compare the Full Economics, Not Just the Purchase Price or Projected Rent
Investors entering a new market should apply the same financial assumptions to both options. A property with a more attractive advertised rent-to-price ratio can become a weaker investment after financing, repairs, vacancies, travel, and management are included.
| Decision factor | Expand in an existing market | Add a Richmond rental |
|---|---|---|
| Geographic exposure | More capital tied to the same regional conditions. | Potentially reduces reliance on the original market, but adds unfamiliar local variables. |
| Rent assumptions | Existing local knowledge may help, but current property-level comps are still needed. | Requires Richmond-specific comps, concession awareness, and realistic lease-up assumptions. |
| Operating costs | Established vendor and management relationships may already exist. | Budget for local management, maintenance, property oversight, and any owner travel or setup costs. |
| Financing and reserves | Additional borrowing can change loan eligibility and liquidity needs. | The same portfolio-wide financing test applies, plus the new property's actual taxes, insurance, and capital needs. |
Start with attainable annual rent, then account for vacancy, property taxes, insurance, owner-paid utilities, HOA expenses, routine maintenance, management, and turnover to estimate operating performance. Model larger capital replacements, debt service, and available cash reserves separately. For comparisons of cash-on-cash return, use the actual cash invested, including down payment, closing costs, and initial work.
Financing can be a constraint before the property even reaches the market. For example, Fannie Mae's reserve guidance generally calls for six months of reserves for an investment-property transaction evaluated through Desktop Underwriter, with additional reserve calculations when the borrower owns multiple financed properties. Requirements depend on the loan and borrower; a lender should confirm the actual terms before an offer.
Our experience is that monthly cash flow and long-term wealth creation are related but different measures. Principal reduction and potential appreciation can affect total return, while an unexpected major repair or turnover can absorb months of apparent cash surplus. Neither optimistic appreciation nor an unusually strong advertised yield should substitute for an adequately funded operating plan.
Why Local Property Management Matters More When the Owner Lives Elsewhere
Buying the property is only one decision. The owner also needs a system that can prepare and market it, coordinate showings and screening, handle resident communication, manage repairs, track financial activity, and respond when a physical visit is required. The owner's location should not determine whether those tasks can be completed.
At PMI James River, we pay attention to factors that broad rent estimates may miss. For example, in-unit laundry and off-street parking can materially affect how a Richmond-area single-family home competes when similar listings provide those features. After a listing goes live, we also distinguish between too few inquiries, inquiries that fail to become showings, and showings that do not produce qualified applications. Those problems do not necessarily have the same solution.
In one Richmond-area management transition, an owner came to us after the previous manager had advertised a rental for roughly 100 days without generating a showing or application. We revised the marketing approach and actively managed pricing. After a $100 asking-rent reduction, six showings were scheduled, and the home was subsequently leased to qualified residents. That is one property's experience, not a promised result, but it illustrates why local execution belongs in the investment calculation.
For remote owners, professional management can preserve the distinction between owning the investment and personally operating every part of it. Our guide to managing a Richmond rental from out of state explains the systems involved, including property access, maintenance coordination, documentation, and owner visibility.
What Should an Investor Do Before Choosing Richmond or Another Property?
A practical decision starts with an identifiable property and a consistent acquisition test:
- Define the purpose. Is the goal geographic diversification, dependable income, long-term equity growth, or a combination?
- Verify the rent. Compare genuinely similar nearby rentals, current incentives, property condition, amenities, and likely marketing timing.
- Confirm financing and cash needs. Obtain actual lending terms, closing-cost estimates, insurance information, and realistic repair and reserve assumptions.
- Evaluate the operation. Establish who will coordinate leasing, access, maintenance, resident issues, financial reporting, and owner decisions after closing.
- Compare complete returns. Use the same annual expense, financing, vacancy, and capital assumptions for the Richmond option and the next-best property elsewhere.
Investors who already own several Richmond rentals do not necessarily need to leave the region just to add variety. A different property type or a carefully selected property in another part of the metro may improve the portfolio's mix while preserving established local management. That is not the same as diversifying into another regional economy, but it may better serve the investor's actual objective.
For an investor considering a purchase in Richmond City, Henrico, Chesterfield, or Hanover, the most useful first step is often to test the property's achievable rent rather than guess at a metropolitan average. Request a free Richmond rental analysis from PMI James River for a property under consideration or already owned. A property-specific rent range and operating discussion provide a stronger starting point for deciding whether Richmond belongs in the portfolio.
Published: November 19, 2026